Choosing the Best Money App in 2026: A Practical Buyer’s Guide
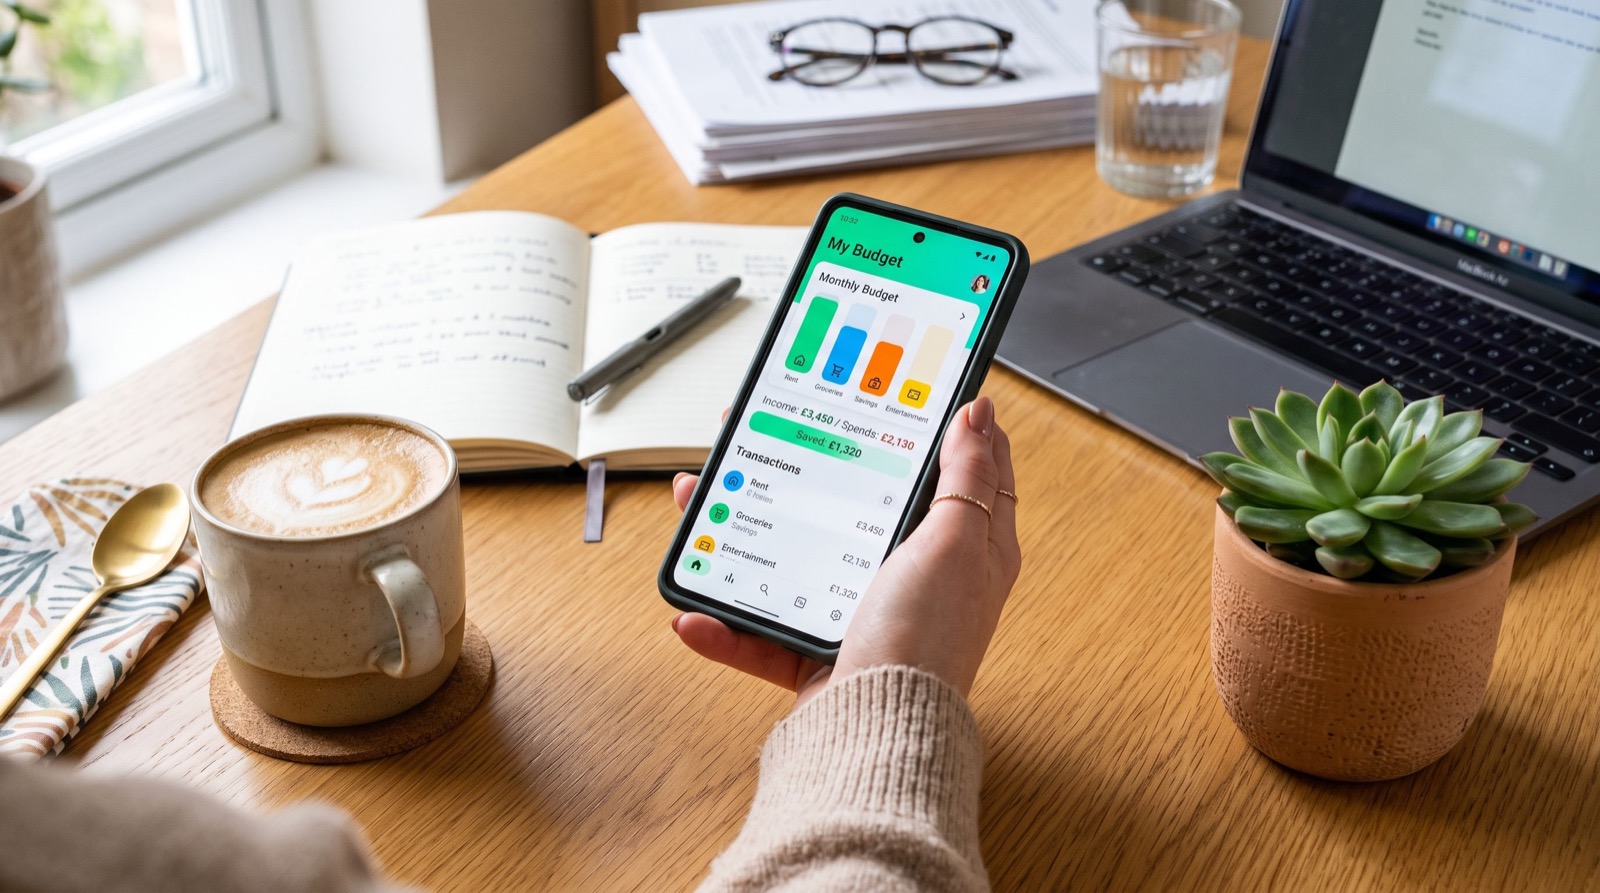
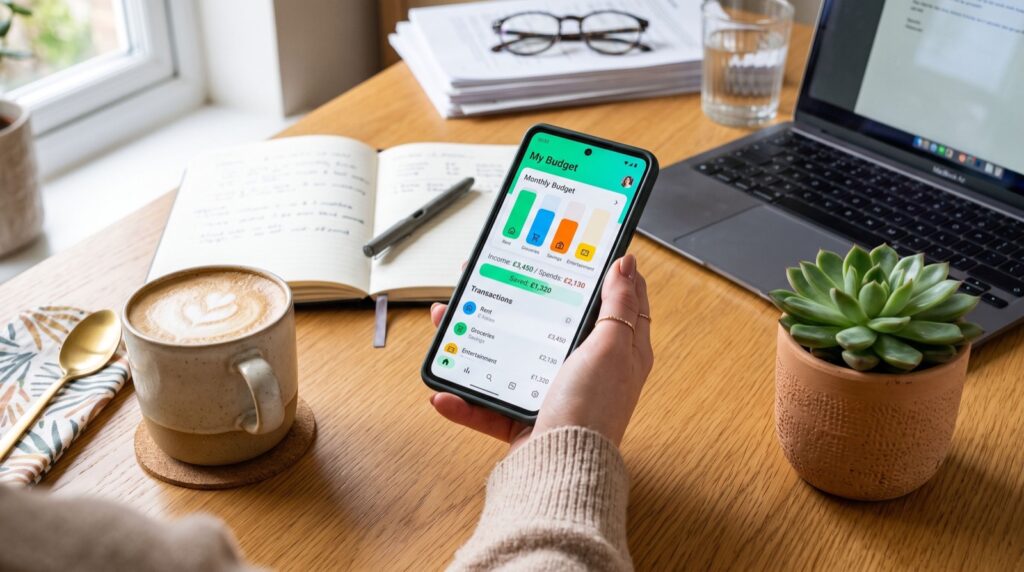
Picking the best money app used to mean comparing two or three budgeting tools. In 2026, app stores are flooded with dozens of options promising to “fix your finances” overnight, and most of them collect more data than they return in value. The right choice depends less on flashy features and more on how well an app matches your actual money habits.
This guide walks through what really separates a genuinely useful app from a pretty interface, so you can choose confidently instead of downloading five apps and giving up on all of them.
What Makes a Money App Worth Keeping
Most people delete a finance app within the first two weeks. Usually it’s not because the app lacks features — it’s because setup friction or confusing categorization makes checking it feel like a chore.
Before downloading anything, decide what problem you actually need solved:
- Do you need help tracking where money goes, or help actively saving more of it?
- Do you want automatic bank syncing, or do you prefer manual entry for better awareness?
- Are you managing money solo, or do you need shared visibility with a partner or family?
- Do you want investment tracking bundled in, or a dedicated app just for spending?
Answering these first narrows dozens of options down to two or three realistic contenders, which is far less overwhelming than browsing an app store’s “top finance apps” list cold.
How Do You Know If a Money App Is Actually Secure?
Security should never be an afterthought when an app has full read access to your bank accounts. Look for apps that use read-only bank connections through established aggregators, support multi-factor authentication, and never ask for your actual bank login password directly inside the app itself.
The National Institute of Standards and Technology publishes widely referenced digital identity and authentication guidelines that reputable fintech companies build their security models around; you can review the public framework at nist.gov. If an app’s privacy page can’t clearly explain its encryption and data-sharing practices, treat that as a red flag rather than fine print to skip.
Comparing Common Types of Money Apps
Not every app is built for the same job. The table below breaks down the main categories so you can match the tool to your actual goal rather than picking whatever ranks highest in an app store search.
| App Type | Best For | Bank Sync | Free Tier |
|---|---|---|---|
| Budget Tracker | Daily spending awareness | Yes, usually | Often limited |
| Automated Savings App | Building savings passively | Yes | Varies |
| Debt Payoff Planner | Structured loan/credit payoff | Sometimes | Usually basic |
| All-in-One Finance Dashboard | Net worth + investments view | Yes | Rarely full-featured |
Round-ups comparing the best money apps on the market are a useful shortcut here, since they typically test real bank-sync reliability rather than just listing marketing claims.
Free vs. Paid Money Apps: Is the Upgrade Worth It?
Many money apps use a freemium model where the free tier handles basic tracking, while paid tiers unlock bill negotiation, investment tracking, or advanced reports. Whether the upgrade is worth it depends on how much manual work the free version still leaves you doing.
- If you’re still manually categorizing more than a few transactions a week, a paid tier with smarter auto-categorization may pay for itself in saved time.
- If you only check your balance occasionally, the free tier is usually plenty.
- If bill negotiation or subscription-cancellation features are included, compare the subscription cost against what those features typically save per year.
According to consumer research published by the Federal Trade Commission, unused or forgotten subscriptions quietly cost households real money every year, which is exactly the kind of leak a good money apps subscription tracker is designed to catch — see the FTC’s consumer guidance at ftc.gov.
Beyond Budgeting Apps: Comparing Other Everyday Purchases
The same comparison discipline that helps you choose a money app applies to other recurring purchase decisions too. For example, shoppers researching business or home communication equipment often need the same side-by-side approach — checking specs, warranty terms, and after-sales support before committing a budget to any one option.
If you’re weighing a similar decision for office hardware, working with reputable service experts who lay out clear comparisons upfront saves the same kind of wasted money that an unused finance app subscription would.
Questions to Ask Before You Commit to an App
A free download costs nothing upfront, but handing over bank access still deserves a short checklist before you link any account. A few extra minutes of research here can save weeks of frustration later.
- Does the app clearly state how it makes money if the core features are free?
- Can you export your data easily if you decide to switch apps later?
- Does customer support include a real human option, not just an automated chatbot?
- Are recurring subscription charges clearly disclosed before the trial period ends?
- Does the app work reliably on both a phone and a desktop browser, in case your phone is lost or being repaired?
Running through these five questions before committing takes less time than setting up the app itself, and it filters out a surprising number of apps that look polished in screenshots but fall apart on basic transparency.
It also helps to read a handful of recent app store reviews rather than the overall star rating alone. A 4.5-star rating built mostly on reviews from 2023 tells you little about how the company is handling customer support or bugs right now, in 2026, after several rounds of updates.
Red Flags That Mean You Should Uninstall
- The app pushes high-interest credit offers disguised as “personalized recommendations.”
- Customer support is unreachable or outsourced entirely to a chatbot with no escalation path.
- The privacy policy allows broad data sharing with unnamed “third-party partners.”
- App reviews mention sudden unexplained charges after a free trial.
Frequently Asked Questions
Which money app is best for someone just starting out?
A simple budget tracker with automatic bank syncing and a genuinely free tier is usually the best starting point in 2026, since it builds the habit of checking in without overwhelming a new user with advanced features.
Are free money apps actually safe to use?
Many free apps are safe as long as they use read-only bank connections and clearly disclose how they monetize the free tier, often through optional premium upgrades rather than selling raw transaction data.
Do I need more than one finance app?
Most people only need one for daily tracking, though some add a second dedicated app for a specific goal like debt payoff or investment tracking once the basics are under control.
How do I switch apps without losing my financial history?
Export your transaction history as a CSV before canceling the old app, since most new apps can import that file during setup rather than making you start tracking from zero.
Final Word
The best money app in 2026 isn’t the one with the most features — it’s the one you’ll actually open every week. Start by defining the one problem you need solved, check the security basics, and only pay for an upgrade once the free tier genuinely stops being enough.